Finance Lease
Structured term financing aligned directly with revenue generation. Full VAT is claimable upon commencement. On-balance-sheet finance recorded as an asset and liability under IFRS 16 and standard accounting practice policies.
Finance Lease in South Africa
Dynamic Rental Solutions offers Finance Lease structures for South African businesses acquiring capital equipment. Under a finance lease, full VAT is claimable upon commencement, providing immediate cash-flow advantages for VAT-registered enterprises.
This structure represents on-balance-sheet finance, recorded as an asset and liability on your balance sheet in full compliance with IFRS 16 and all South African and international accounting practice policies.
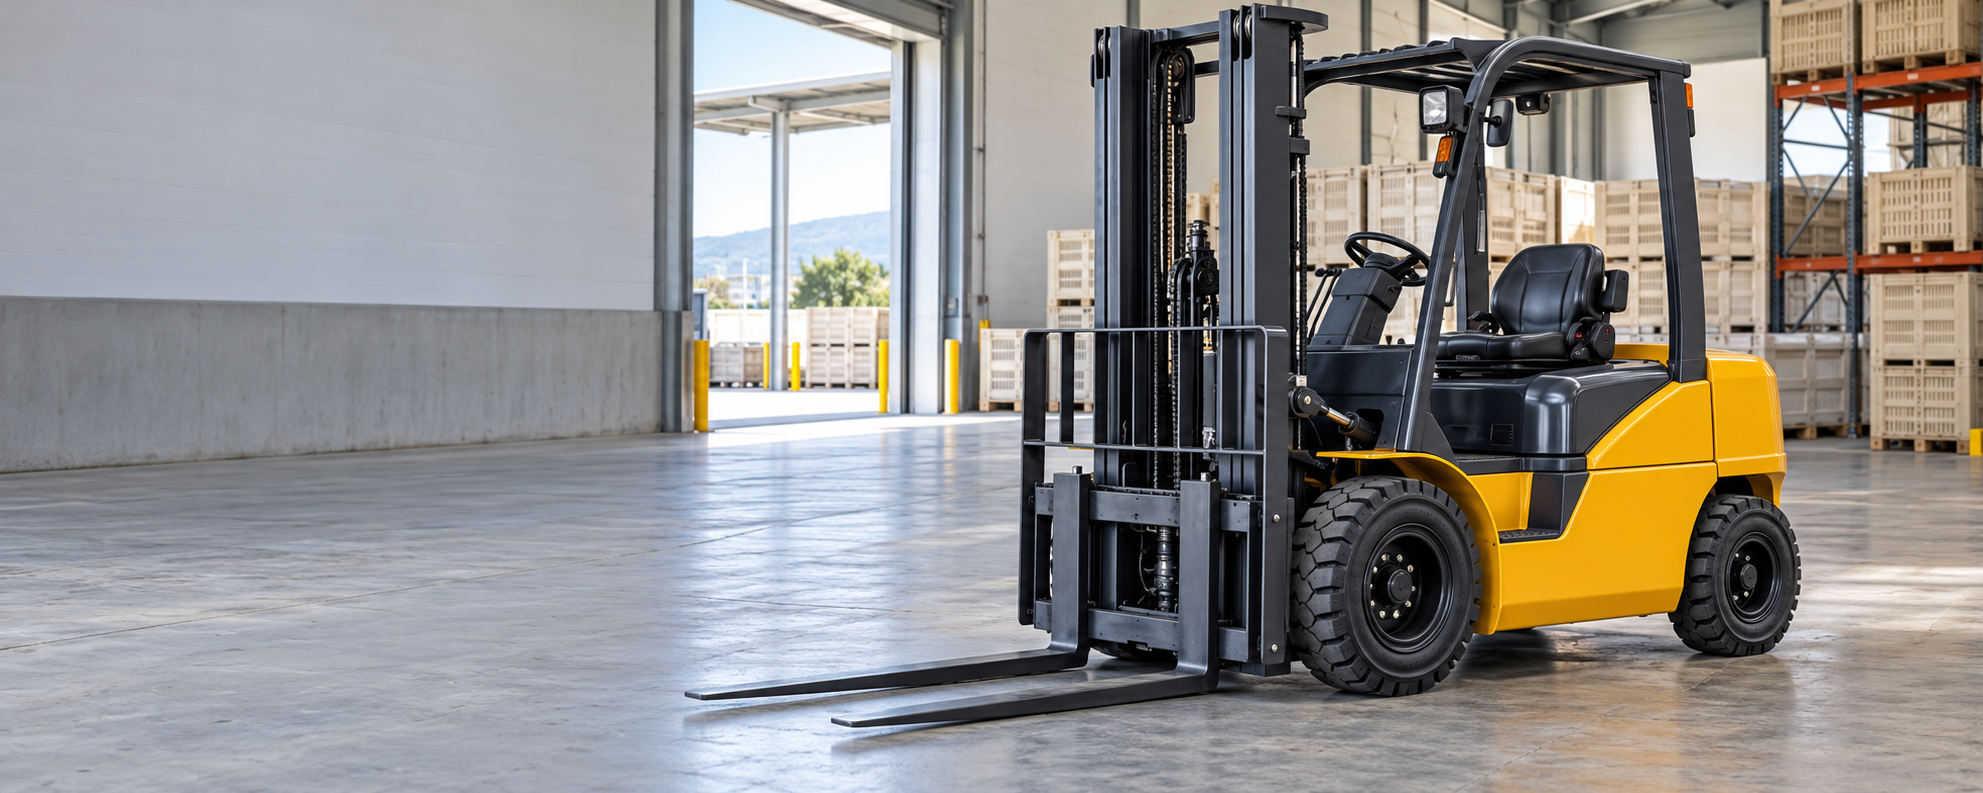
The finance lease enables businesses to acquire higher-value machinery, forklifts, tractors and Modula warehouse automation with fixed monthly instalments over 12–60 months while claiming capital wear-and-tear allowances.
Is the full VAT claimable upfront?
Yes — full VAT is claimable upon commencement of the finance lease for VAT-registered vendors, rather than month-by-month, significantly boosting upfront liquidity.
How is it treated on the balance sheet under IFRS 16?
The finance lease is recorded on balance sheet as a right-of-use asset and a corresponding lease liability in accordance with IFRS 16 and all recognised South African and international accounting practice policies.
How Finance Lease works
A finance lease provides structured capital financing for higher-value equipment where full VAT is claimable upon commencement of the agreement, delivering substantial upfront cash-flow benefits for VAT-registered businesses.
As on-balance-sheet finance, the equipment is recorded as a right-of-use asset and corresponding liability on your balance sheet in accordance with IFRS 16 and applicable accounting practice policies, allowing you to claim depreciation and wear-and-tear allowances while enjoying fixed monthly instalments over 12–60 months.
Key benefits
Full VAT claimable upon commencement
Claim the entire 15% VAT upfront on transaction commencement, optimising early cash flow.
On-balance-sheet finance (IFRS 16)
Recorded as an asset and liability on your balance sheet in accordance with IFRS 16 and all accounting practice policies.
Depreciation & wear-and-tear allowances
Claim capital wear-and-tear deductions (Section 11(e) / 12C) alongside interest expense deductions.
Predictable monthly commitments
Fixed, budgetable instalments across 12–60 months.
For VAT-registered vendors, 100% of the VAT is claimable upon commencement of the finance lease rather than spread over the monthly rentals. Under IFRS 16 and standard accounting practice policies, the equipment is recorded as a right-of-use asset and corresponding liability on your balance sheet, allowing capital wear-and-tear allowances.
How it works
- 1We structure the term, deposit and payment profile around your operational cash-flow cycle.
- 2Full VAT is invoiced and claimable upon commencement of the agreement.
- 3The asset and lease liability are capitalised on your balance sheet under IFRS 16 / accounting standards.
- 4You make predictable monthly instalments while depreciating the asset across its economic life.
Is this right for you?
- Higher-value capital equipment (forklifts, tractors, Modula VLMs, heavy machinery)
- VAT-registered businesses seeking full upfront VAT recovery upon commencement
- Organisations reporting on-balance-sheet assets and liabilities under IFRS 16
- Operations wanting wear-and-tear tax allowances and structured asset ownership
Questions we hear
Is the full VAT claimable upfront?
Yes — full VAT is claimable upon commencement of the finance lease for VAT-registered vendors, rather than month-by-month, significantly boosting upfront liquidity.
How is it treated on the balance sheet under IFRS 16?
The finance lease is recorded on balance sheet as a right-of-use asset and a corresponding lease liability in accordance with IFRS 16 and all recognised South African and international accounting practice policies.
Can the payment profile be tailored?
Payment profiles can be structured to suit your cash-flow requirements, subject to credit approval and the agreed transaction structure.
Explore Finance Lease
Structure a facility with a DRS specialist
Finance structures, ownership arrangements, VAT treatment and accounting implications depend on the applicable agreement, legislation and the customer's circumstances. All financing is subject to credit approval and final contractual terms. Customers should obtain independent accounting and tax advice where appropriate.
Related DRS solutions & guides
Rent-to-Own
Rent today, own at term end · Fully tax deductible
Invoice Discounting
Turn invoices into immediate capital
Agricultural Equipment
Tractors, harvesters, implements, irrigation systems and packhouse machinery — practical agricultural equipment solutions supported by structured finance that helps farmers and packhouses acquire the machinery they need to improve efficiency and expand capacity.
Returnable Packaging
Plastic crates, pallets and returnable packaging fleets that reduce single-use waste and capital friction — financed as an operating asset, not a balance-sheet burden.
Ready to move your business forward?
Get a structured finance quote in minutes. No upfront fees, no obligation — just a clear path to the asset your operation needs.